Apartment Building & Multifamily Financing
Apartment BuildingFinancing for
5+ Unit Properties
Purchase, refinance, and complex multifamily financing evaluated through property performance, borrower circumstances, documentation, and transaction structure — for owners and investors across California.

What are you trying to do?
Start with the situation closest to yours — it carries straight into the conversation below.
Our approach
From Complex to Possible
A strong apartment property or borrower can still encounter financing complications. The first step is identifying what is actually creating the obstacle.
Property
Income, occupancy, condition, value-add plans, property performance.
Borrower
Financial profile, credit, liquidity, ownership experience.
Documentation
Rent roll, operating statements, tax information, financial presentation.
Structure
Ownership, entity structure, existing debt, loan purpose.
Mortgage Bankers' role is not to bypass underwriting. The objective is to understand the file, identify issues, prepare the information, and explore appropriate financing paths.
Have a property you want to discuss?
Discuss Your Property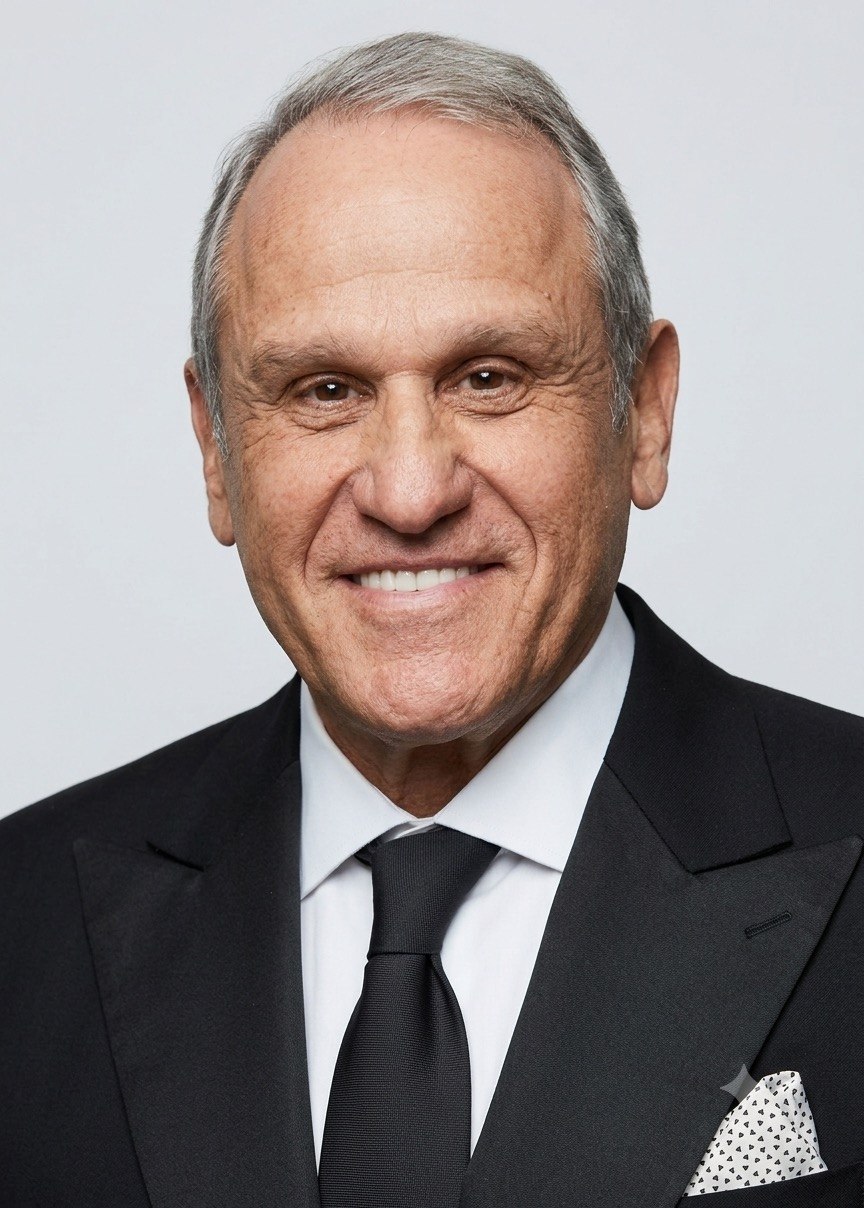
Shahram Sean Elyaszadeh
Founder, Mortgage Bankers Corporation
Multifamily financing situations rarely come down to one number. Four decades of evaluating property economics and borrower circumstances shapes how a file gets reviewed before it ever reaches a lender:
- Recognizing issues earlier, before they slow down a transaction
- Evaluating the complete financing situation — property, borrower, and structure together
- Understanding what a given lender is likely to focus on
- Preparing a financing presentation appropriately
- Exploring reasonable, appropriate financing paths
What lenders typically evaluate
Multifamily underwriting commonly considers several factors together, not any single number in isolation:
Rent roll & occupancy
Current leases, unit mix, in-place rents versus market rents, and vacancy history.
NOI & DSCR
Net Operating Income and the resulting Debt Service Coverage Ratio, calculated from trailing operating statements.
Reserves & liquidity
Post-closing reserves for debt service, capital repairs, or vacancy, as required by the specific lender and program.
Sponsor experience
Prior ownership or management experience with income property, particularly relevant for larger buildings or higher leverage.
Property condition
Physical condition, deferred maintenance, and any capital improvement plan factored into underwriting.
Borrower & entity documentation
Personal and/or entity financial statements, tax returns, and formation documents where the property is held in an entity.
Why NOI and DSCR matter
NOI (Net Operating Income) is what the property earns after applicable operating expenses — the starting point lenders use to evaluate a multifamily property on its own economics.
DSCR (Debt Service Coverage Ratio) compares that qualifying income to the required debt service, showing how comfortably the property's income covers the loan payment.
This is a general explanation of two common underwriting concepts, not a calculator or financial advice. Actual NOI/DSCR treatment, required ratios, and eligibility depend on the specific lender and program.
Process & timeline expectations
Understand
Property and objective.
Evaluate
Property economics and borrower circumstances.
Diagnose
Identify complications or missing information.
Structure
Explore appropriate financing paths.
Prepare
Organize information for review.
Lender review
Underwriting and lender decision.
Timing, terms, approval, and closing depend on the applicable lender, underwriting, property, and documentation. Mortgage Bankers does not control lender approval, rates, or closing dates.
Working with Mortgage Bankers Corporation
Mortgage Bankers Corporation was founded in 1985 by Shahram Sean Elyaszadeh and has served California clients from its Los Angeles office for over four decades, holding California DRE corporate license #01375131. Program availability varies by transaction, lender, and property.
Request a property financing review
Four short steps. Nothing you enter here is an application, approval, rate quote, or commitment to lend.
Apartment building financing FAQs
What property types qualify as an apartment building for financing purposes?
Lenders generally distinguish 2-4 unit residential properties from 5+ unit multifamily buildings, which are typically underwritten on a commercial/income basis. Eligibility, occupancy requirements, and property condition standards vary by lender and loan type.
How is an apartment building's income reviewed?
Lenders commonly review the rent roll, trailing operating statements, vacancy history, and resulting NOI and DSCR. No single metric determines eligibility on its own, and requirements vary by lender and program.
Do lenders require cash reserves for an apartment property?
Many lenders request post-closing reserves to cover debt service, capital repairs, or vacancy, in addition to the down payment or equity requirement. Reserve requirements vary by lender, loan type, and property condition.
Does ownership or management experience matter for multifamily financing?
Some lenders consider a borrower's or sponsor's prior experience owning or managing income property, particularly for larger buildings or higher-leverage requests. This is one of several underwriting factors, not a standalone qualifier.
What documentation is typically requested for a purchase or refinance?
Common documentation includes the rent roll, trailing operating statements, current leases, property tax and insurance records, entity formation documents where applicable, and standard borrower financial and identification documents. Exact requirements vary by lender and transaction.
How early should I start preparing before an apartment loan matures?
Many owners begin the conversation several months ahead of a loan maturity so there is time to review current property performance, gather documentation, and understand realistic options before a deadline becomes pressing. Exact timing depends on the property and existing loan.
Can a strong, well-performing property still have difficulty getting refinanced?
Yes. Financing difficulty can come from the property, the borrower's documentation, the ownership structure, or the transaction itself — not only from weak property performance. Identifying the actual source of complexity is part of preparing a workable financing path.
What if another lender already declined the loan or could not complete it?
A prior decline or an incomplete transaction with another lender does not automatically rule out financing elsewhere. It is useful information for evaluating what happened and whether a different structure, lender, or documentation approach is appropriate.
Does a consultation guarantee financing approval or terms?
No. A consultation is a general discussion of your property, financials, and goals. It is not an application, approval, rate quote, or commitment to lend. Approval, terms, and funding are subject to full underwriting and lender requirements.
What helps make the first review more productive
Preparing the following in advance can help, though exact requirements are always set by the applicable lender:
- Current rent roll and unit mix
- Trailing 12-month (or available) operating statements
- Current loan information, for a refinance
- Property tax bills and insurance information
- Entity formation documents, if the property is or will be held in an LLC or partnership
- Borrower financial statements, tax returns, and identification
- A summary of any planned capital improvements or repositioning strategy